
Key Takeaways
- Compare the total repayment, not only the monthly EMI.
- Ask whether interest is calculated on a flat or reducing balance basis.
- Check processing fees, applicable taxes and missed-payment terms before signing.
- A treatment pause or cancellation does not automatically cancel your loan.
IVF EMI interest charges can feel confusing when you are already thinking about tests, medicines and appointments. You deserve a clear treatment estimate and a separate written explanation of borrowing costs, without pressure to sign immediately.
IVF EMI Charges: Interest, Processing Fees and Late-Payment Terms
For couples in Delhi NCR, spreading treatment payments may help with monthly budgeting. But a manageable instalment is not necessarily an affordable loan. A longer repayment period can lower the EMI while increasing the total interest.
Keep two figures separate: what your medical care may cost, and what borrowing that money will cost. The clinic explains treatment billing; the named lender should explain the finance agreement.
How IVF EMI interest charges are calculated
Ask whether the quoted rate is annual, and whether it uses a flat or reducing balance calculation. These terms affect your repayment even when two advertised rates look similar.
Flat interest versus reducing balance
With flat interest, interest is generally calculated on the original principal throughout the agreed tenure. With reducing balance interest, it is calculated on the outstanding principal as repayments reduce it.
For example, two offers may show the same annual rate and tenure. If one uses flat interest and the other uses reducing balance, their total repayments can differ. Request repayment schedules rather than comparing rates alone.
- What amount will actually be financed?
- Is the interest rate fixed or variable?
- Is the calculation flat or reducing balance?
- What is the annual percentage rate, or APR?
- What is the total amount payable across the full tenure?
APR helps you compare the annualised borrowing cost, including interest and applicable charges. Ask for the lender’s Key Facts Statement, where applicable, and check which charges it includes. Contingent charges, such as late-payment fees, need separate attention.
What does “no-cost EMI” mean?
A no-cost offer may involve an interest subsidy or an adjusted discount. It does not automatically mean there are no processing fees, taxes or other conditions. Compare the upfront payment option with the complete EMI repayment amount.
Ask whether choosing EMI changes any treatment discount. Request the explanation in writing, including who provides the subsidy and what happens to it if treatment is cancelled.
Processing fees and other deductions
A processing fee may be collected separately, added to the financed amount or deducted before disbursal. If it is deducted, confirm that the remaining disbursal covers the intended clinic payment.
If a fee is financed, you may also pay interest on it. Ask for a breakup of applicable taxes rather than assuming every component has the same tax treatment.
| Charge or term | What to check | Why it matters |
|---|---|---|
| Processing fee | Amount, tax and collection method | May increase borrowing or the upfront payment |
| Interest | Annual rate, calculation method and APR | Determines much of the borrowing cost |
| Optional cover | Consent, premium and cancellation terms | Can add to your total repayment |
| Late-payment charge | Trigger, calculation and any applicable tax | Adds cost when payment is overdue |
| Mandate return charge | Lender and bank terms | May apply when an automatic debit fails |
| Early closure | Eligibility and applicable charges | Affects the benefit of repaying sooner |
Do not accept an unexplained deduction. If insurance or another add-on appears in the documents, ask whether it is optional and whether declining it changes the offer.
Late-payment terms deserve a careful read
A failed automatic debit can happen because of insufficient funds, a mandate problem or an account issue. Depending on the agreement, the lender may levy a return charge and a separate overdue-payment charge. Your bank may also charge you.
Ask when payment becomes overdue and whether any grace period exists. Do not assume there is one. For regulated lenders, applicable RBI rules govern penal charges; request a written explanation of how these are applied.
- Check the EMI date against your salary credit date.
- Keep enough balance before the debit is scheduled.
- Save payment receipts and lender messages.
- Ask how a failed debit can be paid manually without duplicate collection.
- Contact the lender early if you expect difficulty paying.
Missed repayments may be reported to credit bureaus and affect future borrowing. Paying the clinic does not settle a lender’s overdue EMI. Confirm the correct payment channel before transferring money.
If an automatic debit fails despite sufficient funds, keep the bank statement and raise a complaint promptly. Ask how any disputed charges or credit reporting will be reviewed.
Match the loan to your treatment estimate
IVF EMI interest charges are only one part of affordability. The treatment estimate should explain what is included and what may be billed separately, based on your prescribed care.
For IVF treatment in Lajpat Nagar, ask about consultations, investigations, stimulation medicines, monitoring, egg retrieval, anaesthesia, laboratory work and embryo transfer. Do not assume one package includes every stage.
Embryo freezing, storage, a later frozen embryo transfer or additional procedures may have separate charges. If ICSI treatment is advised, ask how it affects the estimate. A doctor will decide what is medically appropriate; finance availability should not decide your treatment.
A useful check is whether your household could still manage repayments if additional medicines were needed or treatment took longer than expected. Keep room for ordinary expenses, not just clinic bills.
What if treatment pauses or you repay early?
A cycle may be postponed or cancelled for medical reasons. Treatment may also not lead to pregnancy. Neither situation automatically ends your repayment obligation, because the loan and treatment arrangements are separate.
- Ask which treatment payments are refundable and at what stage.
- Check whether unused funds return to you or directly to the lender.
- Ask when a refund would reduce the loan balance.
- Confirm whether interest continues while a refund is being processed.
- Request written part-payment and early-closure terms.
Prepayment charges depend on the loan type, lender and applicable rules. After full repayment, obtain a closure confirmation and check that the account is reported as closed.
A practical check before visiting Lajpat Nagar
At Pravi Global IVF, E-3, 3rd Floor, Lajpat Nagar 2, New Delhi, you can ask for a treatment-cost discussion before making financial commitments. Confirm current payment arrangements directly; do not assume EMI approval or availability.
Many visitors use Lajpat Nagar metro, which is on the Violet and Pink lines. Couples travelling from Noida or Gurugram can plan an interchange according to their starting station. If driving, allow extra time depending on traffic, especially around market hours.
Bring your estimate and any lender offer. Compare IVF EMI interest charges at home, away from appointment-day pressure. Both partners should have time to read the documents.
Frequently Asked Questions
Are IVF EMI interest charges the same for everyone?
No. Offers can vary by lender, credit assessment, financed amount and tenure. Compare your written offer rather than relying on someone else’s rate.
Does a low EMI mean a cheaper loan?
Not necessarily. A longer tenure can reduce the monthly payment while increasing total interest. Compare APR, fees and total repayment together.
Can I stop EMIs if IVF is unsuccessful?
Usually, repayments remain due under the loan agreement regardless of the treatment outcome. Any explicit refund arrangement must be checked separately in writing.
Will one missed payment affect my credit record?
It may, depending on reporting and the payment status. Contact the lender promptly, clear the overdue amount and ask how the account will be reported.
Should I sign the loan before seeing the treatment estimate?
First request a written estimate and discuss possible additional costs. Then review the loan terms. You should understand both before committing.
For a treatment-cost discussion at Pravi Global IVF, call +91 80091 50040 or book an appointment. Bring your questions about treatment billing and finance terms.
Medical Reviewer
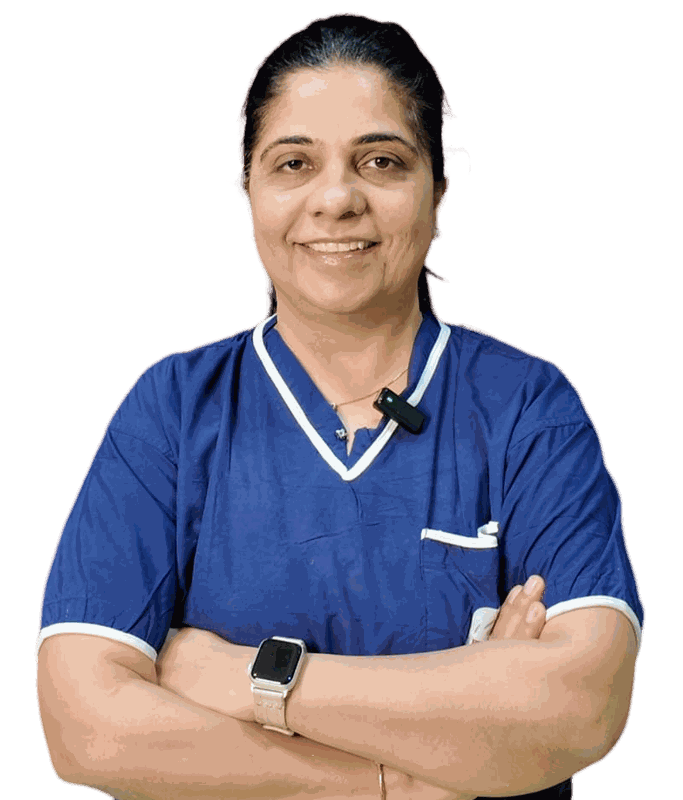
Dr. Monica Sachdev
Dr. Monica Sachdev is a leading IVF specialist in Delhi with over 18 years of experience in reproductive medicine. She is dedicated to providing evidence-based fertility care and has helped thousands of families achieve parenthood.
Ready to Start Your Fertility Journey?
Our friendly team at Pravi IVF is here to stand by you, listen to your story, and help you through every single step.